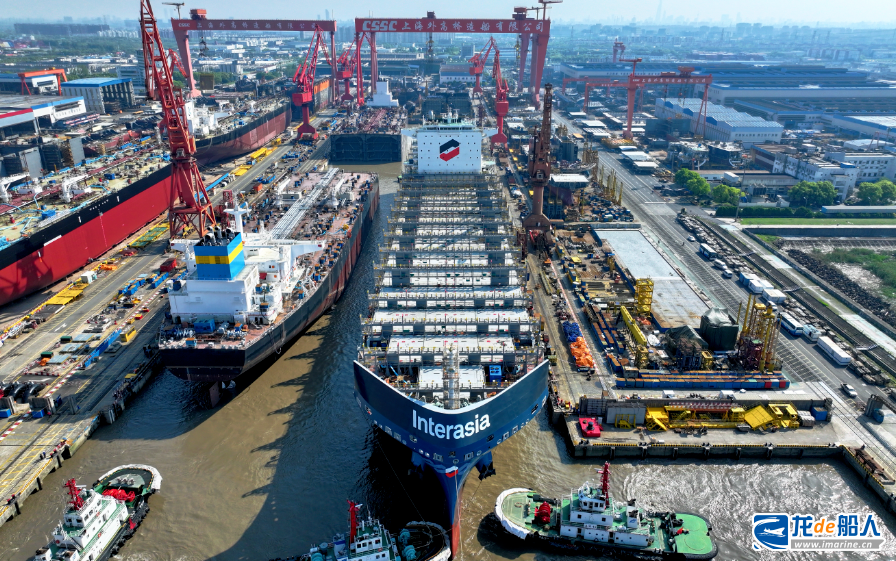
Chinese shipowners and shipbuilders are driving an unprecedented new-vessel construction cycle, pushing the global shipbuilding orderbook to an all-time high.
Based on a report released by Clarksons on October 30, global shipyard order books have reached 226 million compensated gross tonnages (CGT), with an estimated contract value of $700 billion. The current order volume is three times that of 2020 and represents a 24% increase compared to 2025. This figure has far surpassed the historical record of 225 million corrected gross tons set in September 2008 during the previous shipbuilding supercycle.
Stephen Gordon, Managing Director of Clarksons, stated: “The shipbuilding industry is ‘red-hot,’ driven by factors such as persistently high charter earnings, supply chain disruptions stemming from geopolitical issues—which mean more vessels are now required to transport each unit of cargo globally—as well as energy security and resilience, the uneven pace of the green transition, and the renewal of the global fleet.”
Clarkson points out that the current shipbuilding supercycle differs significantly from the one seen in 2008. In terms of gross tonnage (GT), the current orderbook—vessels currently under construction—accounts for approximately 25% of the existing fleet, whereas in 2008, this figure reached as high as 53%.
Meanwhile, compared to 2008, the current orderbook structure is more diversified. The total tonnage of container ships and liquefied gas carriers under construction has doubled and tripled, respectively, while the shares of bulk carriers and oil tankers have declined—from 31% to 17% for the former, and from 25% to 21% for the latter.
Beyond the aforementioned differences, the landscape of the global shipbuilding industry is also undergoing significant change.
In terms of shipbuilding nations—measured by compensated gross tonnage (CGT)—the share of the global orderbook held by Chinese shipyards has doubled, rising from 34% in 2008 to 68% today. Meanwhile, the share held by South Korean shipyards has fallen from 32% to 17%, and that of Japanese shipyards has declined from 18% to 8%.
Stephen Gordon notes: “Driven by significant leaps in productivity, construction quality, and price competitiveness, alongside an expansion in production capacity, China has secured a leading position across all shipbuilding segments—with the exceptions of gas carriers and cruise ships. In the gas carrier sector, South Korean shipyards maintain a dominant position, holding a 60% market share; meanwhile, the cruise ship sector is almost entirely controlled by European shipyards, which command a 97% market share.”
In terms of individual shipyards, six of the world’s top ten by orderbook volume are now located in China—a significant increase from just two in 2008. Among shipbuilding conglomerates, China State Shipbuilding Corporation (CSSC) has risen to become the world’s largest, displacing South Korea’s HD Hyundai Group, which held the top spot in 2008.
Measured in CGT, Hengli Heavy Industries ranked first globally in terms of orderbook volume as of the end of September 2026, with 485 vessels on order—accounting for 11.2% of the global total.