Recently, Banchero Costa compiled a list of the top 15 individual shipyards (excluding shipbuilding groups) globally, ranked by their volume of newbuild orders and orderbooks—measured in compensated gross tonnage (CGT)—with data covering the period up to the end of September 2026.
Top 15 individual shipyards by volume of new orders received
Based on data from Banchero Costa, the top 15 individual shipyards globally in terms of new orders (measured by CGT) for the first nine months of 2026 were all Chinese or South Korean shipyards, comprising 11 Chinese shipyards and 4 South Korean shipyards, as follows:
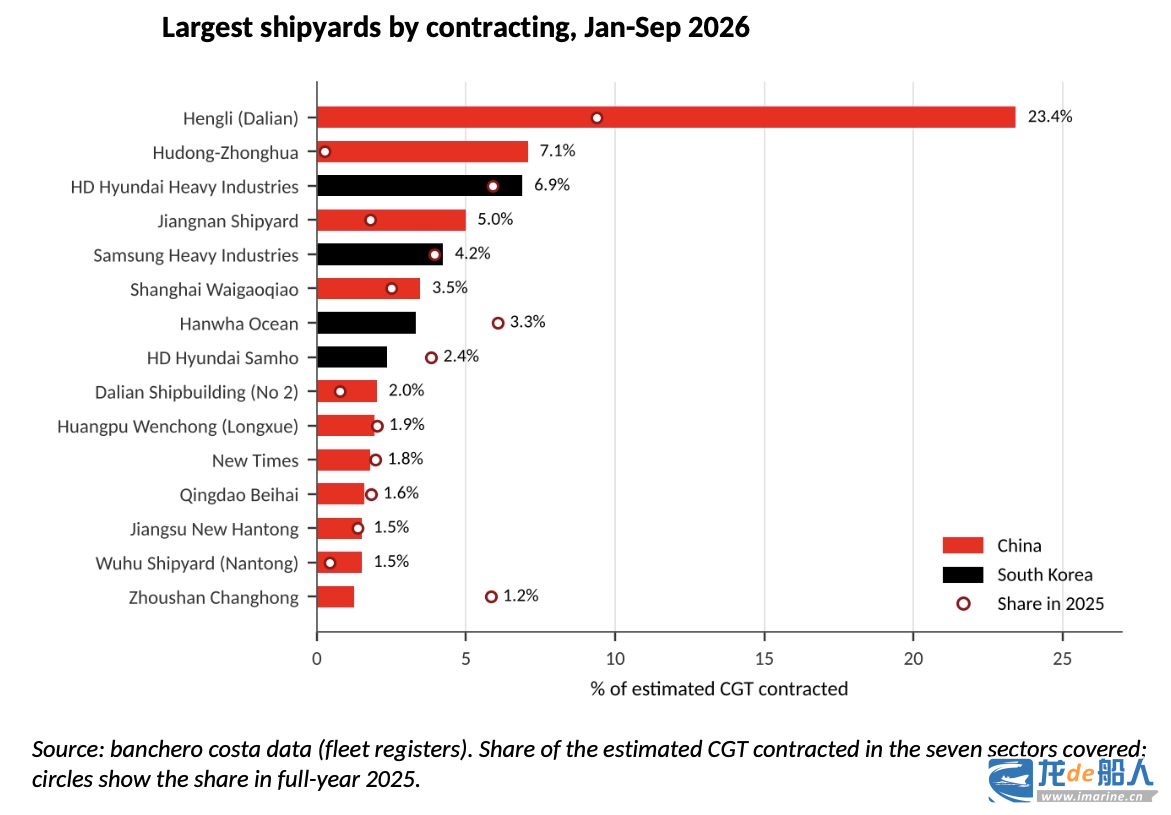
The shipyards ranked first through fifth—Hengli Heavy Industries, Hudong-Zhonghua Shipbuilding, HD Hyundai Heavy Industries, Jiangnan Shipyard, and Samsung Heavy Industries—account for approximately 23.4%, 7.1%, 6.9%, 5.0%, and 4.2% of the global total order volume, respectively.
The shipyards ranked sixth through tenth—Shanghai Waigaoqiao Shipbuilding, Hanwha Ocean, HD Hyundai Samho, Dalian Shipbuilding Industry Corporation (DSIC), and Huangpu Wenchong Shipbuilding—account for approximately 3.5%, 3.3%, 2.4%, 2.0%, and 1.9% of the global total order volume, respectively.
The shipyards ranked eleventh through fifteenth—New Times Shipbuilding, Beihai Shipbuilding, Jiangsu Hantong Ship Heavy Industry Co., Ltd(HT), Wuhu Shipyard, and Zhoushan Changhong International—account for approximately 1.8%, 1.6%, 1.5%, 1.5%, and 1.2% of the global total order volume, respectively.
Top 15 individual shipyards by new order volume
Based on CGT, as of the end of September 2026, the top 15 shipyards in the world by order backlog were also from China and South Korea, including 11 Chinese shipyards and 4 South Korean shipyards, as follows:
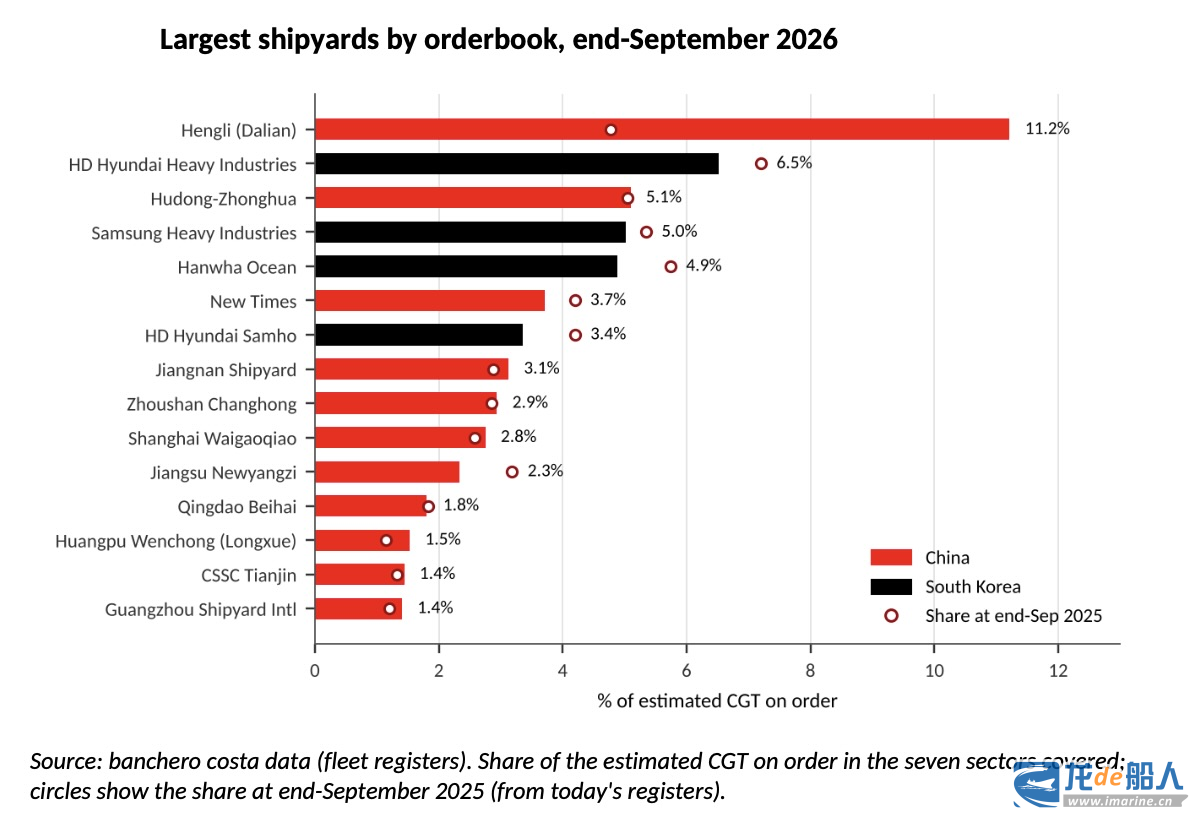
The shipyards ranked first through fifth—Hengli Heavy Industries, HD Hyundai Heavy Industries, Hudong-Zhonghua Shipbuilding, Samsung Heavy Industries, and Hanwha Ocean—account for approximately 11.2%, 6.5%, 5.1%, 5.0%, and 4.9% of the global total of shipbuilding orders on hand, respectively.
The shipyards ranked sixth through tenth—New Times Shipbuilding, HD Hyundai Samho, Jiangnan Shipyard, Zhoushan Changhong International, and Shanghai Waigaoqiao Shipbuilding—account for approximately 3.7%, 3.4%, 3.1%, 2.9%, and 2.8% of the global total of shipbuilding orders on hand, respectively.
The shipyards ranked eleventh through fifteenth—Yangzijiang Shipbuilding, Beihai Shipbuilding, Huangpu Wenchong Shipbuilding, DSIC, and Guangzhou Shipyard International—account for approximately 2.3%, 1.8%, 1.5%, 1.4%, and 1.4% of the global total of shipbuilding orders on hand, respectively.
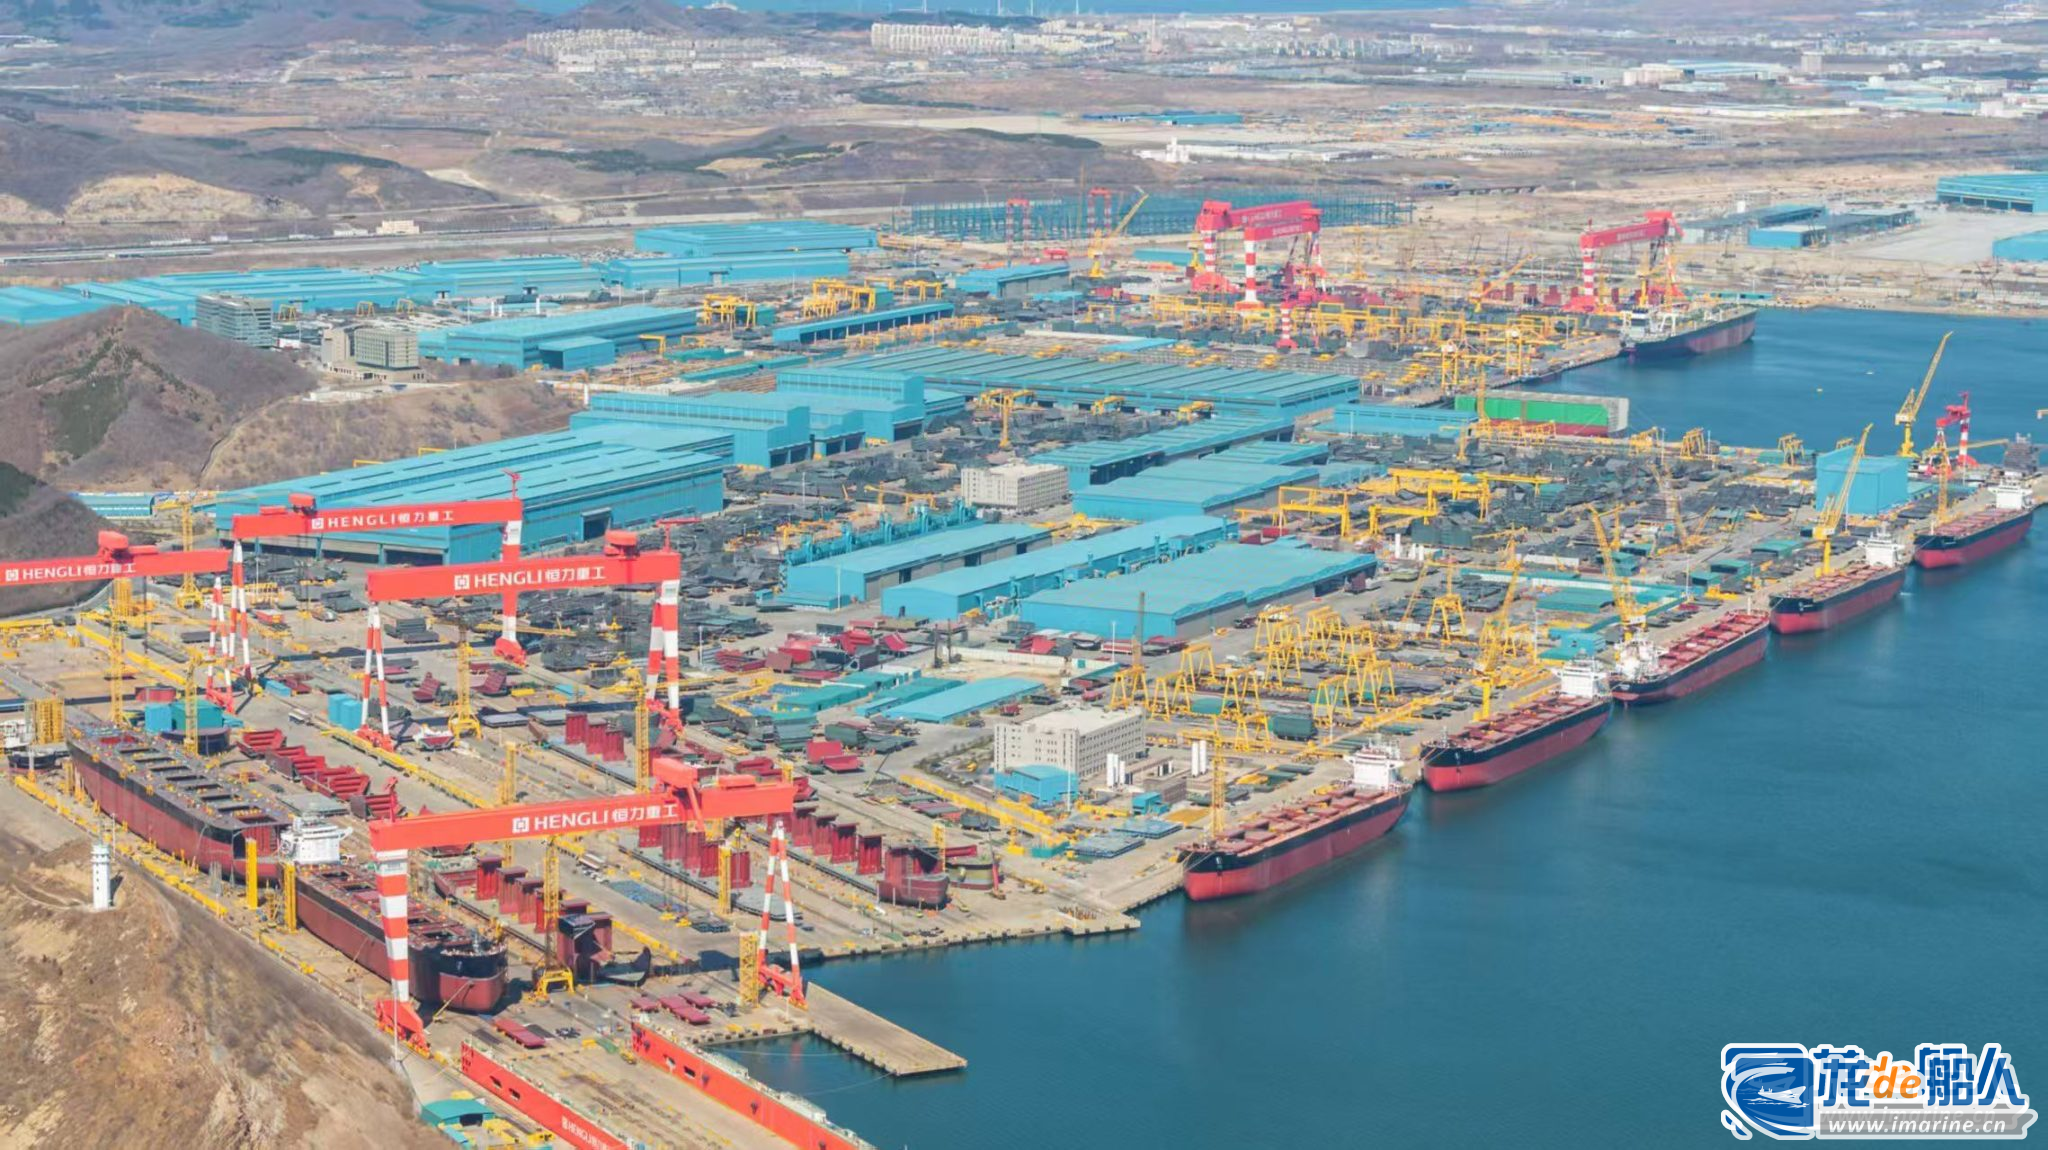
Among the above list, Hengli Heavy Industries stands out, having secured the top position in two key categories. From January to September 2026, the company won orders for 276 new vessels, accounting for approximately 23.4% of the global order volume (in terms of CGT) for that period. By the end of September, its order backlog had grown to 485 vessels—representing 11.2% of the global total—making it the world’s leading individual shipyard.
Meanwhile, the growth in Hengli Heavy Industries’ production capacity is keeping pace with its remarkable surge in new shipbuilding orders.
In terms of vessel deliveries, the company completed 4 ships in 2024 and 17 in 2025. According to the latest data disclosed by Hengli Heavy Industries, it expects to deliver approximately 90 vessels in 2026—a figure exceeding market expectations—with projections for 2027 reaching over 120 vessels.
Furthermore, Banchero Costa estimates that by 2028, Hengli Heavy Industries’ annual delivery volume could reach as high as 200 vessels. In terms of CGT, this single shipyard’s output would account for approximately 12.6% of the total global deliveries across the seven major commercial vessel segments.